Update (September 2026): Omnibus I (Directive (EU) 2026/470, in force 18 March 2026) reset the CSRD: scope is now more than 1,000 employees and more than EUR 450 million net turnover, newly in-scope companies report first on FY2027, listed SMEs are out, and companies under 1,000 employees cannot be asked by customers for more than the VSME standard. The revised ESRS were adopted on 3 July 2026 and, absent objection, enter into force on 10 November 2026.
The re-baselined picture, with the FY2026 options: CSRD After the Omnibus.
EU Corporate Sustainability Reporting Directive (CSRD)
Last Updated: May 2025
The Corporate Sustainability Reporting Directive (CSRD), which entered into force on 5 January 2023, modernizes EU sustainability disclosure obligations and aligns them with global best practices.
🔍 Key 2025 Updates
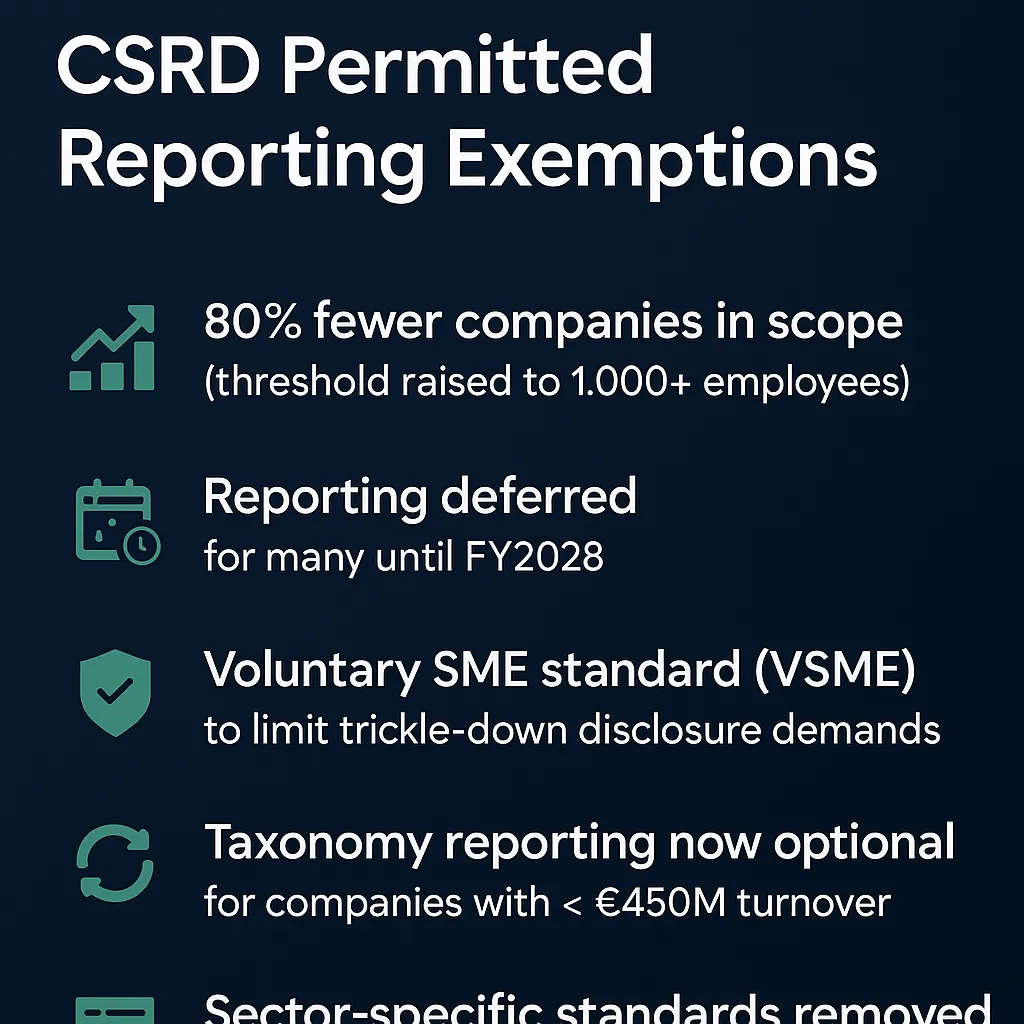
1. Scope Reduction
Companies must now have more than 1,000 employees and meet at least one of the following:
- €50 million in turnover
- €25 million in total assets
This update reduces the number of companies in scope by approximately 80%.
2. Deferred Deadlines
Wave 2 & 3 companies, including listed SMEs and non-EU firms with significant EU operations, now begin reporting in FY2028 (for reports published in 2029).
3. Voluntary SME Reporting (VSME)
SMEs not in scope may report using a simplified voluntary standard developed by EFRAG. This shields them from excessive information requests from large value chain partners.
4. Simplified ESRS Standards
The EU will no longer adopt sector-specific reporting standards. The general cross-cutting ESRS has been simplified and clarified.
5. Taxonomy Reporting Made Voluntary
Companies with <€450 million turnover may opt in to voluntary and partial EU Taxonomy alignment reporting.
6. Limited Assurance Requirement Maintained
The proposed shift toward “reasonable assurance” has been removed. Only limited assurance is required for now.
7. Digital Reporting Mandate
CSRD requires use of a digital taxonomy to ensure reports are machine-readable and comparable.
🧪 Reporting Framework
Companies under CSRD must use the European Sustainability Reporting Standards (ESRS) developed by EFRAG. These build upon global initiatives such as the ISSB and GRI, ensuring compatibility and EU-specific alignment.
🎯 Policy Objective
The CSRD aims to:
- Equip investors and stakeholders with high-quality sustainability data
- Support risk-informed capital allocation
- Reduce administrative burden through harmonized, digital-first disclosure rules