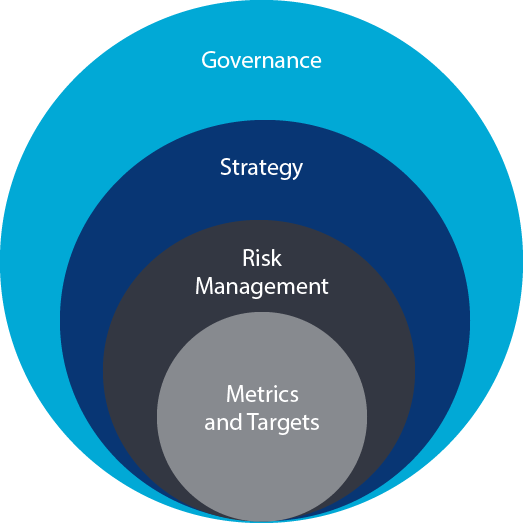
The transition now has a date. The FCA's PS26/19, published 30 September 2026, replaces the TCFD-aligned listing rules with disclosure against the UK Sustainability Reporting Standards, the UK-endorsed ISSB standards, for accounting periods beginning on or after 1 January 2027. The whole framework is comply-or-explain, including climate, with transitional relief of one year for Scope 3 and two years for the wider UK SRS S1 disclosures. The existing TCFD-based rules continue to apply until then.
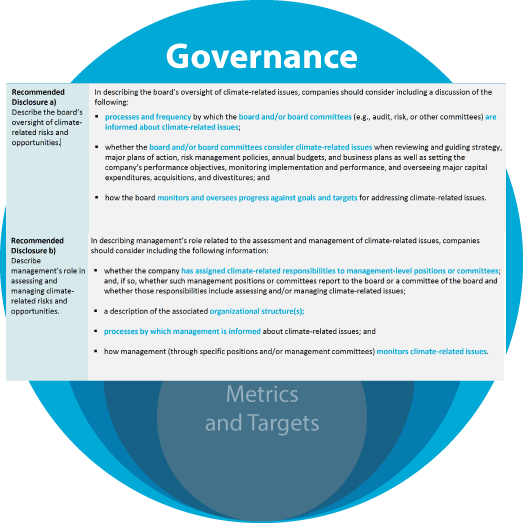
What to do: treat the FY2026 TCFD report as the last one on the old basis. Map your governance, strategy, risk and metrics disclosures to UK SRS S2 now, and decide early where you will explain rather than comply, because an explanation is itself a disclosure investors will read.