Scope
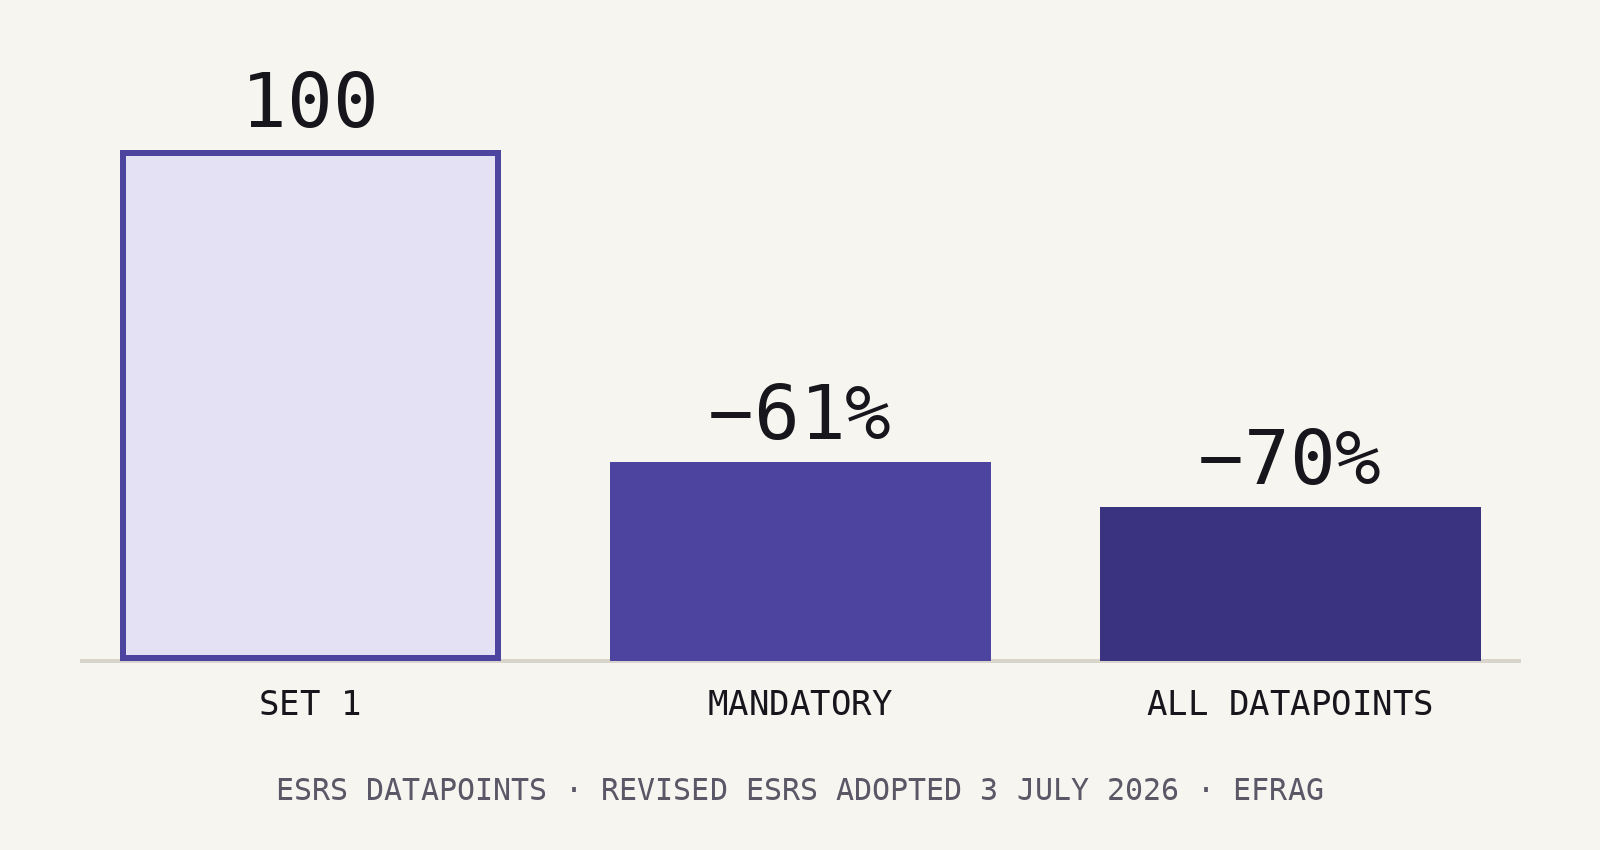
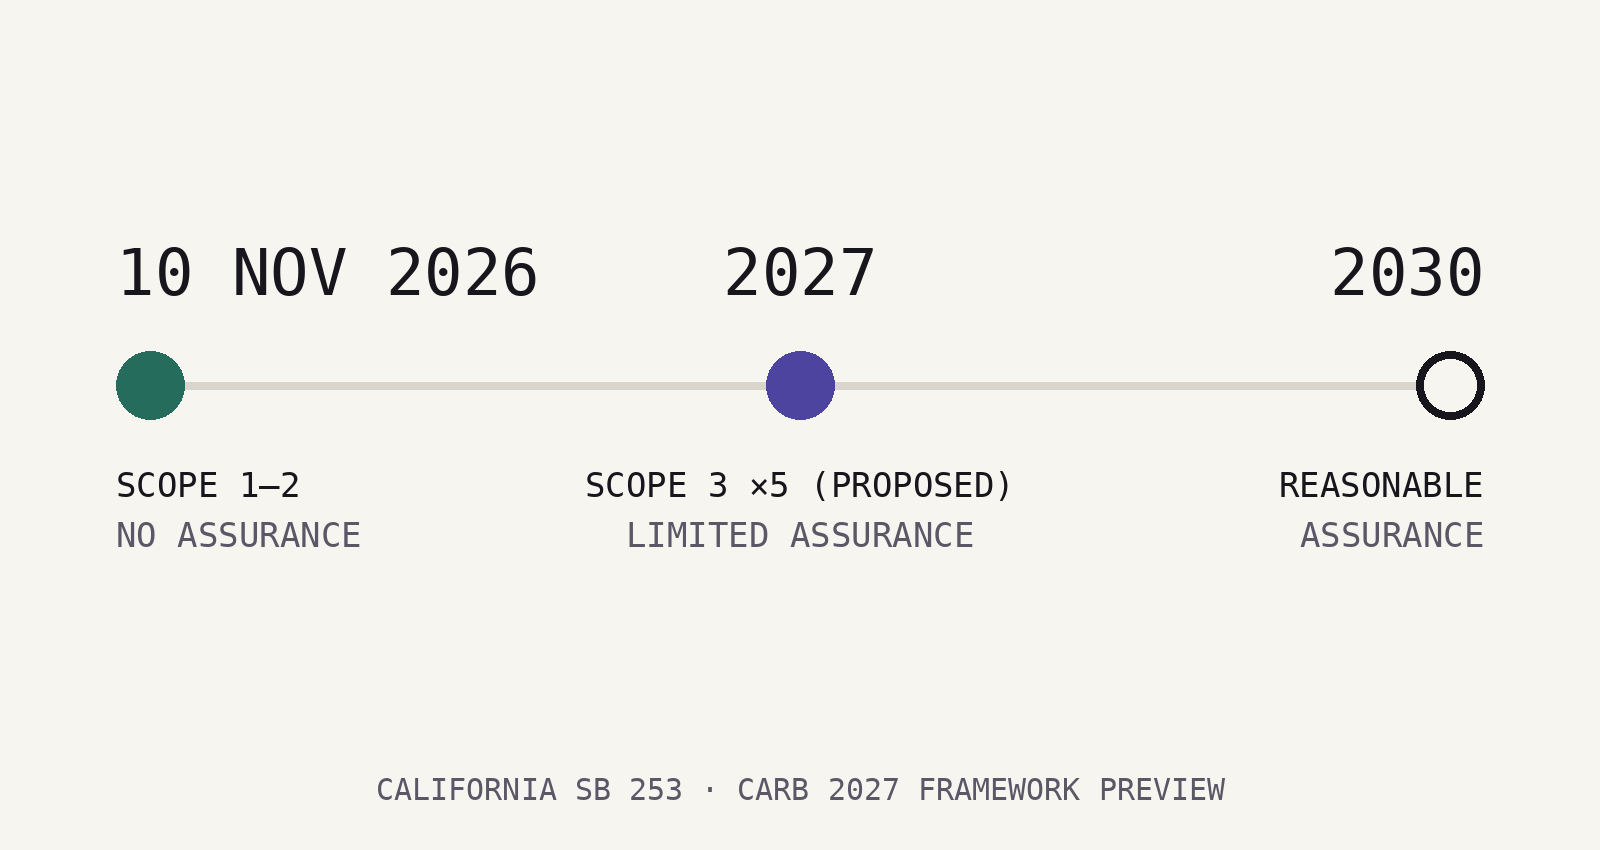
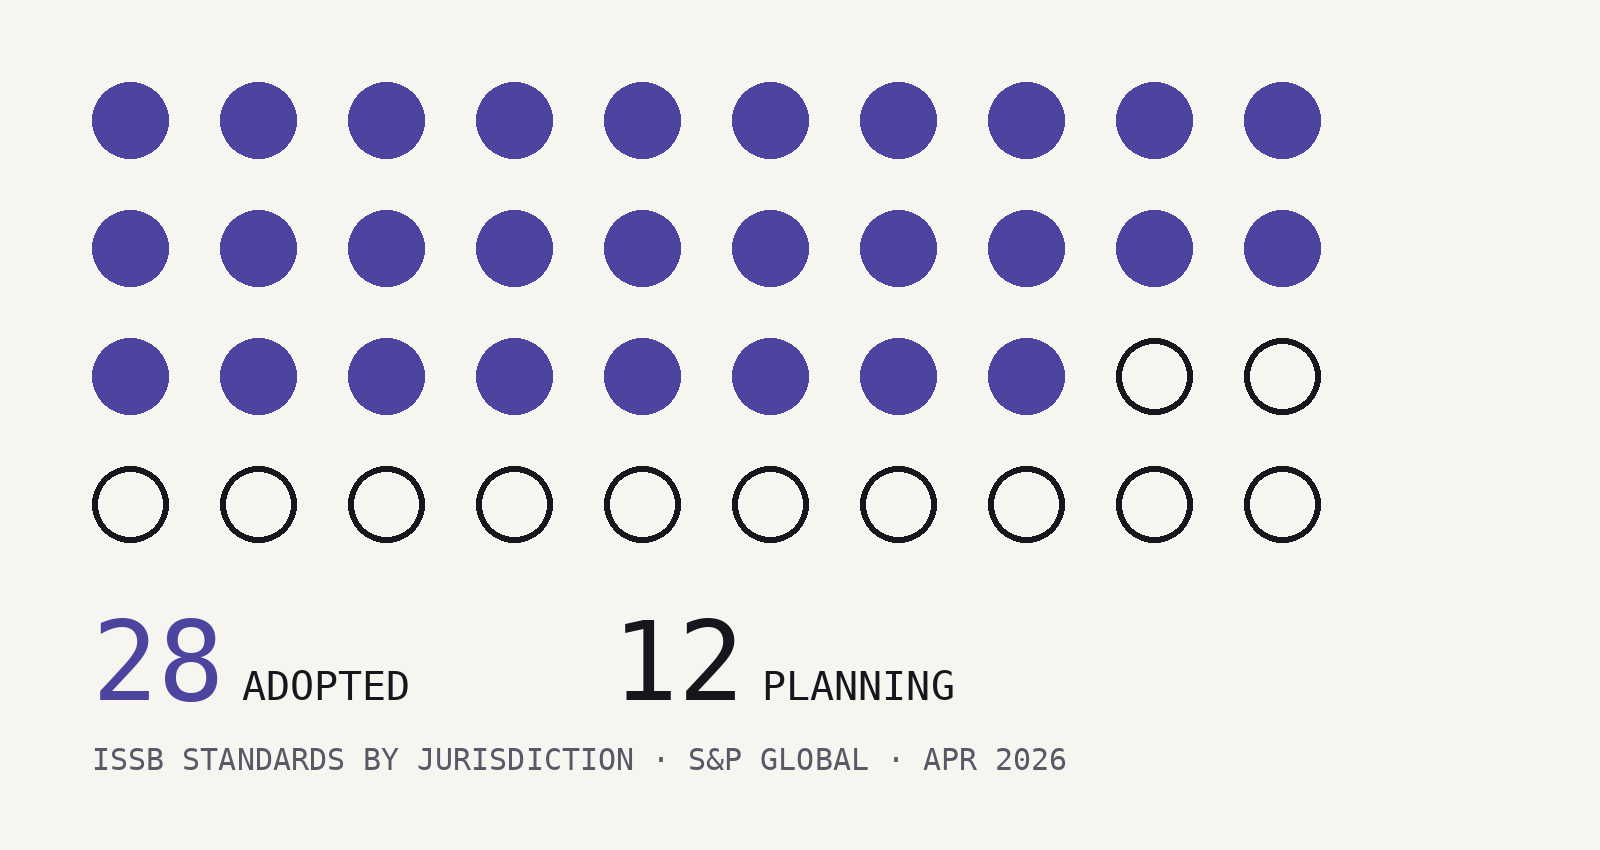
Most disclosure-readiness engagements start with a checklist and end with a PDF nobody actions. We start by pinning down exactly which regime applies to your entities and when — CSRD/ESRS phase-in, ISSB S1/S2 jurisdictional adoption, or California SB 253/261 — because that determination changes everything downstream.
From there: a gap analysis against your current reporting and data capabilities, a remediation roadmap with named owners and dates, and an assurance-readiness review so limited or reasonable assurance isn't a surprise in year two.