Update (September 2026): The Commission adopted the revised ESRS on 3 July 2026. Mandatory datapoints fall by more than 60% and all voluntary datapoints are removed; EFRAG's 28 August 2026 draft list runs to about 530 datapoints with a draft XBRL taxonomy (comments to 23 October). The delegated act enters into force on 10 November 2026 absent objection and applies to financial years beginning on or after 1 January 2027; for FY2026 a company may stay on Set 1, early-adopt in full, or apply Set 1 with selected reliefs.
Full analysis: CSRD After the Omnibus.
The European Sustainability Reporting Standards (ESRS) are a set of standards developed under the mandate of the Corporate Sustainability Reporting Directive (CSRD) by the European Financial Reporting Advisory Group (EFRAG). The ESRS aim to provide a unified framework for sustainability reporting within the European Union, enhancing the consistency, comparability, and reliability of sustainability information provided by companies.
Key characteristics and objectives of the ESRS include:
- Comprehensive Scope: The standards cover a wide range of sustainability topics, including environmental, social, and governance (ESG) issues. They are designed to capture the full spectrum of sustainability impacts, risks, and opportunities faced by companies.
- Double Materiality Perspective: Consistent with the CSRD, the ESRS are based on the concept of double materiality. This means they require reporting not only on how sustainability issues affect the company’s financial performance (financial materiality) but also on the company's impacts on people and the environment (impact materiality).
- Mandatory Application: For companies within its scope, the CSRD mandates the application of the ESRS, making sustainability reporting a legal requirement. This significantly expands the number of companies required to report detailed sustainability information compared to the previous Non-Financial Reporting Directive (NFRD).
- Sector-Specific Standards: Alongside general standards applicable to all reporting entities, the ESRS framework includes sector-specific standards to address the unique sustainability aspects and impacts of different industries.
- Alignment with International Initiatives: While focusing on the needs of the European market, the ESRS aim to align with global sustainability reporting frameworks and standards where possible, facilitating the integration of sustainability reporting into global financial markets.
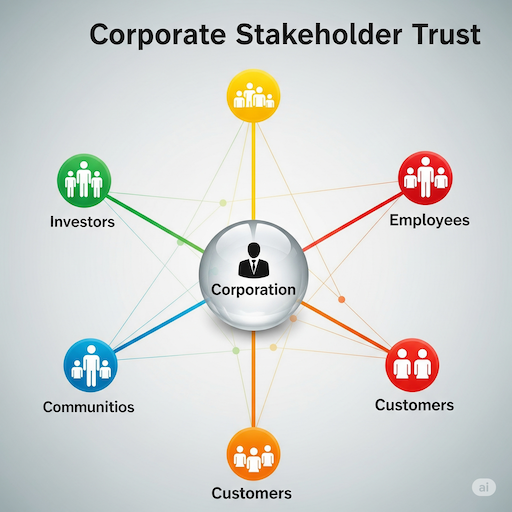
- Enhanced Transparency and Accountability: By standardizing sustainability reporting, the ESRS seek to improve transparency and accountability among companies, providing stakeholders, including investors, customers, and the public, with reliable and comparable information to make informed decisions.
The development of the ESRS and their integration into European corporate reporting practices mark a significant step towards more sustainable economic activities in the EU by ensuring that companies assess and disclose their sustainability performance in a harmonized and comprehensive manner. This initiative is part of the EU's broader sustainable finance framework, which aims to direct capital flows towards sustainable investments to achieve a carbon-neutral, sustainable economy.