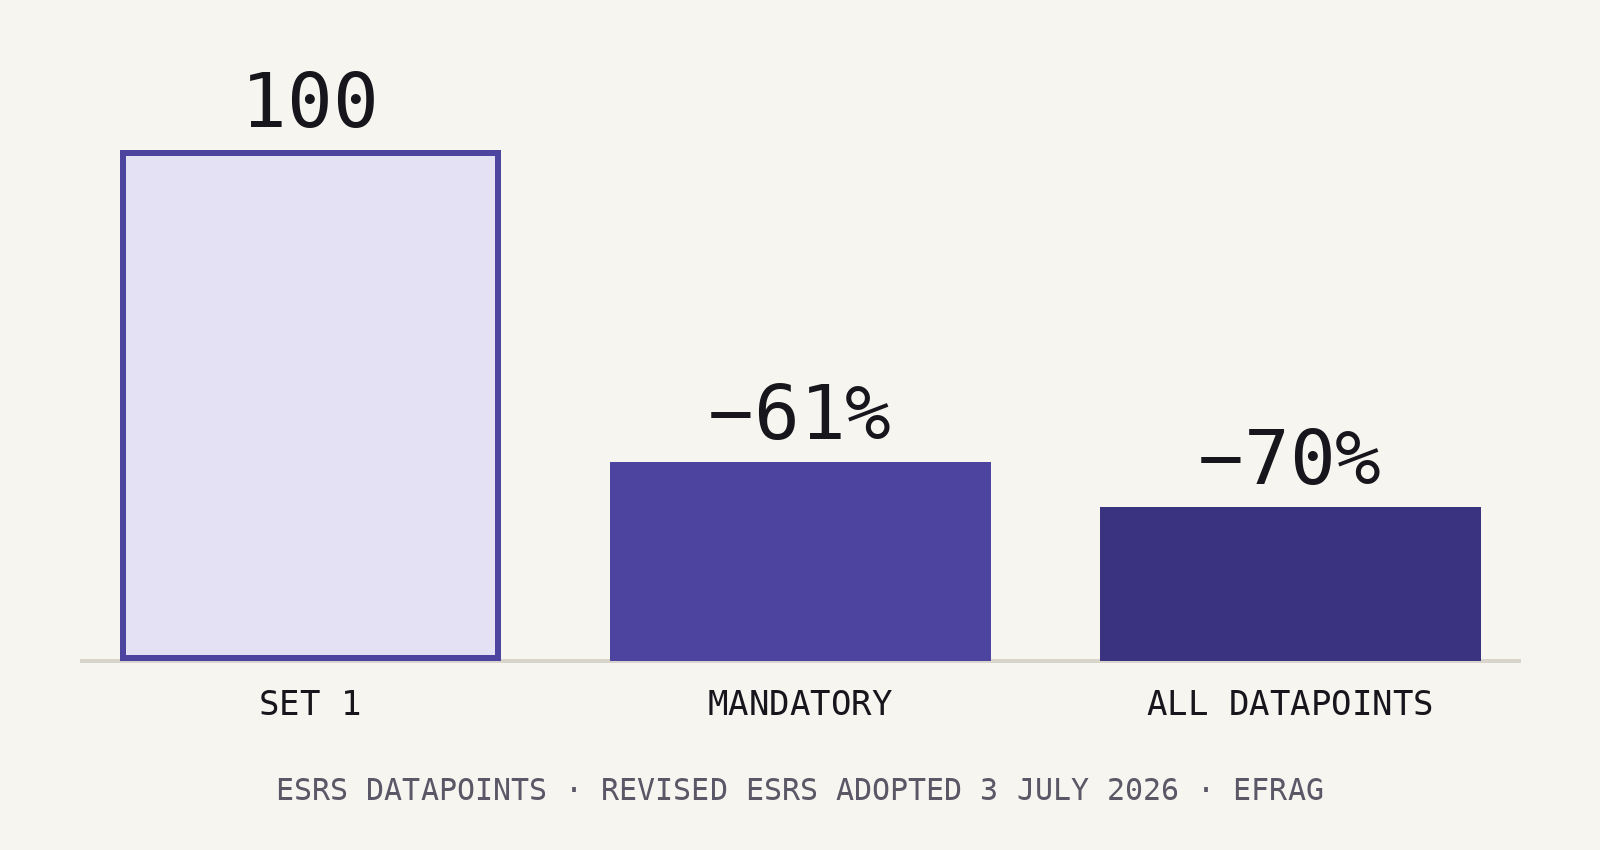
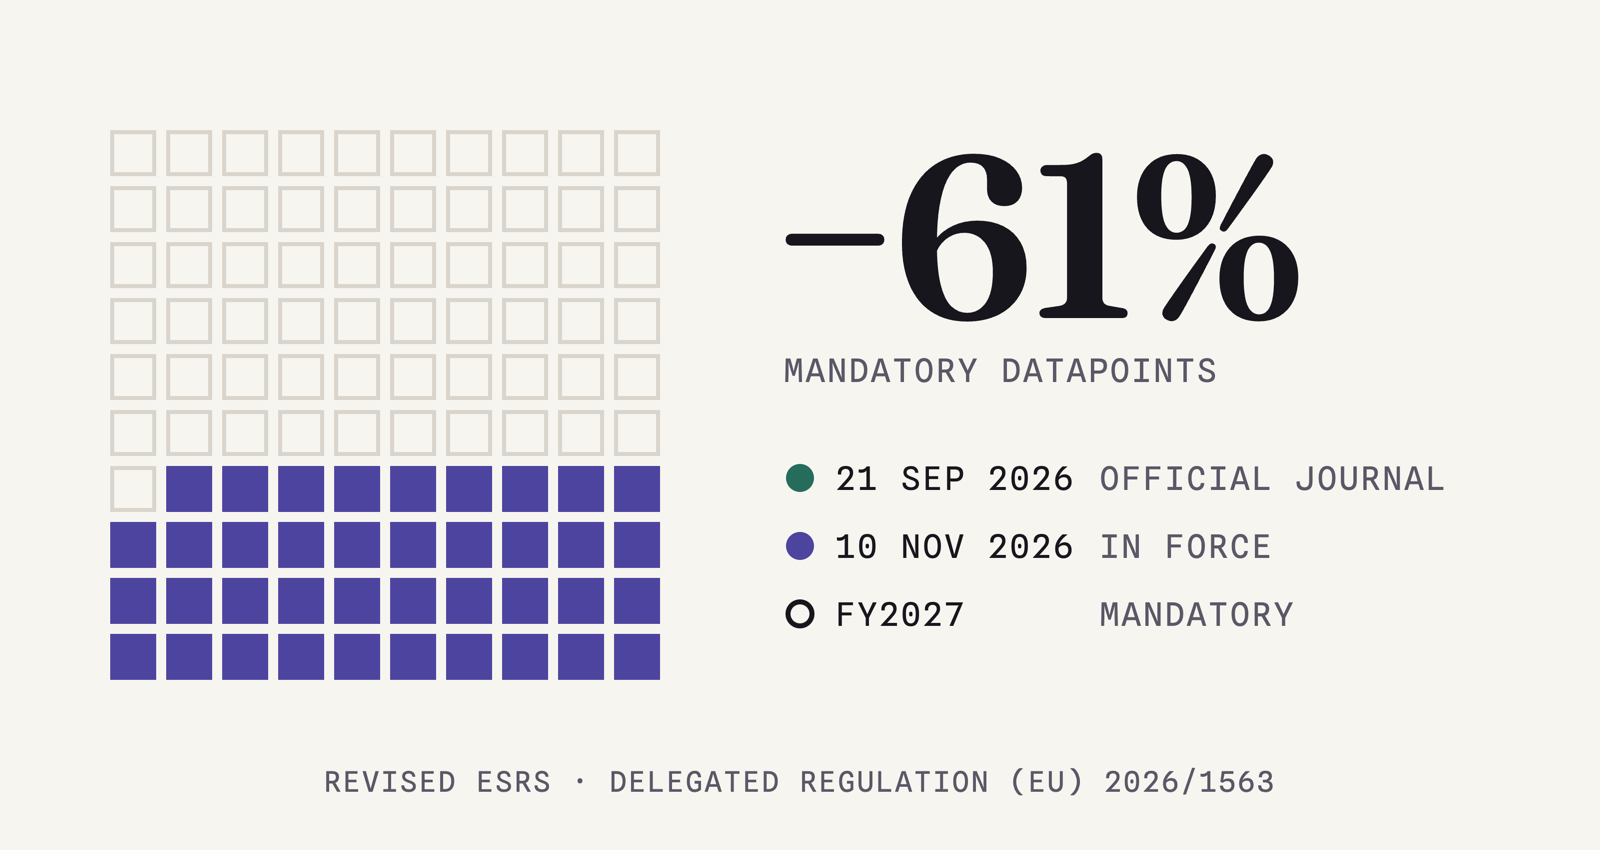
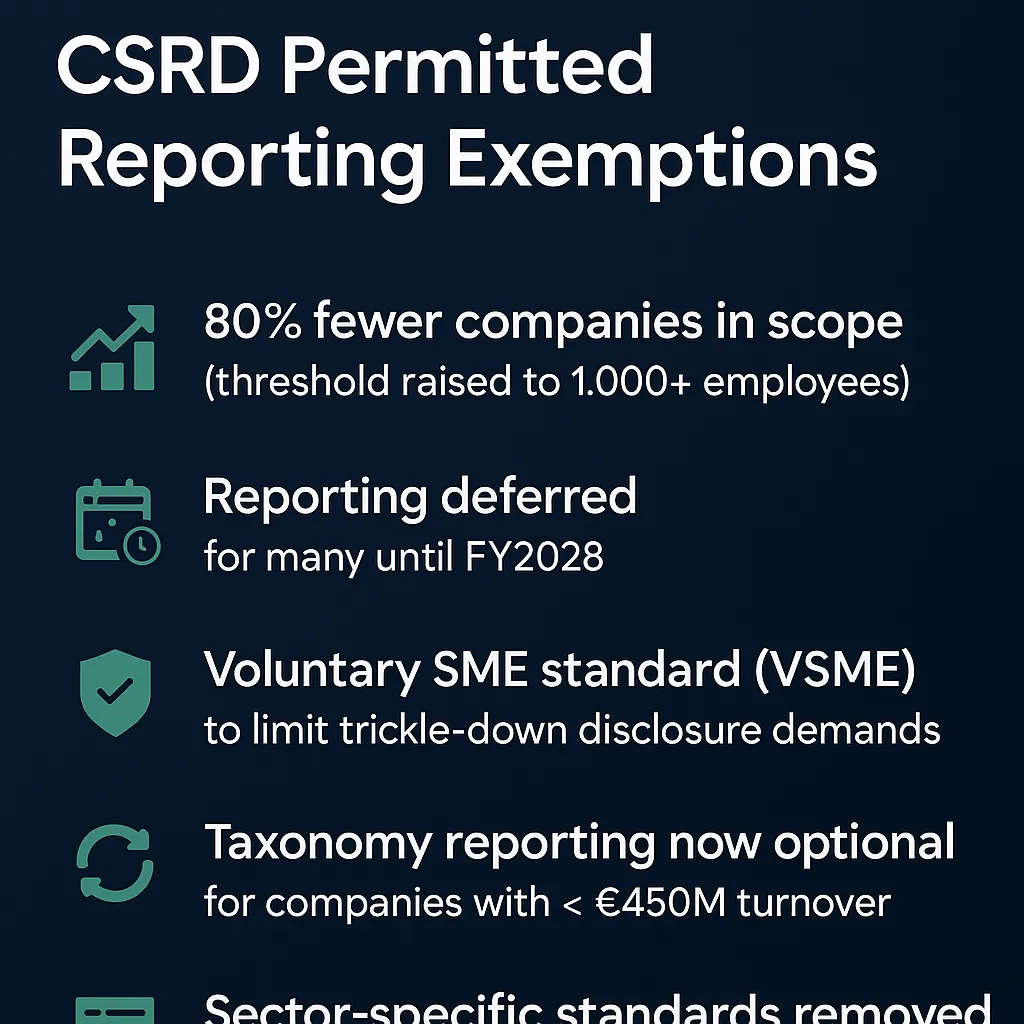
The CSRD most companies scoped in 2024 is not the CSRD in force today. Omnibus I (Directive (EU) 2026/470) replaced the 250-employee test with a two-part threshold of more than 1,000 employees and more than €450 million net turnover, took listed SMEs out of the mandatory regime, and made limited assurance permanent. The revised ESRS (Delegated Regulation (EU) 2026/1563) cut mandatory datapoints by more than 60% and apply to financial years beginning on or after 1 January 2027; they are optional for FY2026.
What to do: re-run the scope test on consolidated numbers for the last two financial years before relying on any 2024 memo. If you are still in scope, decide now whether FY2026 is reported on ESRS Set 1 or the revised standards. If you fell out, keep the inventory and the double materiality assessment and map what remains to VSME, since lenders, customers and other jurisdictions will still ask.