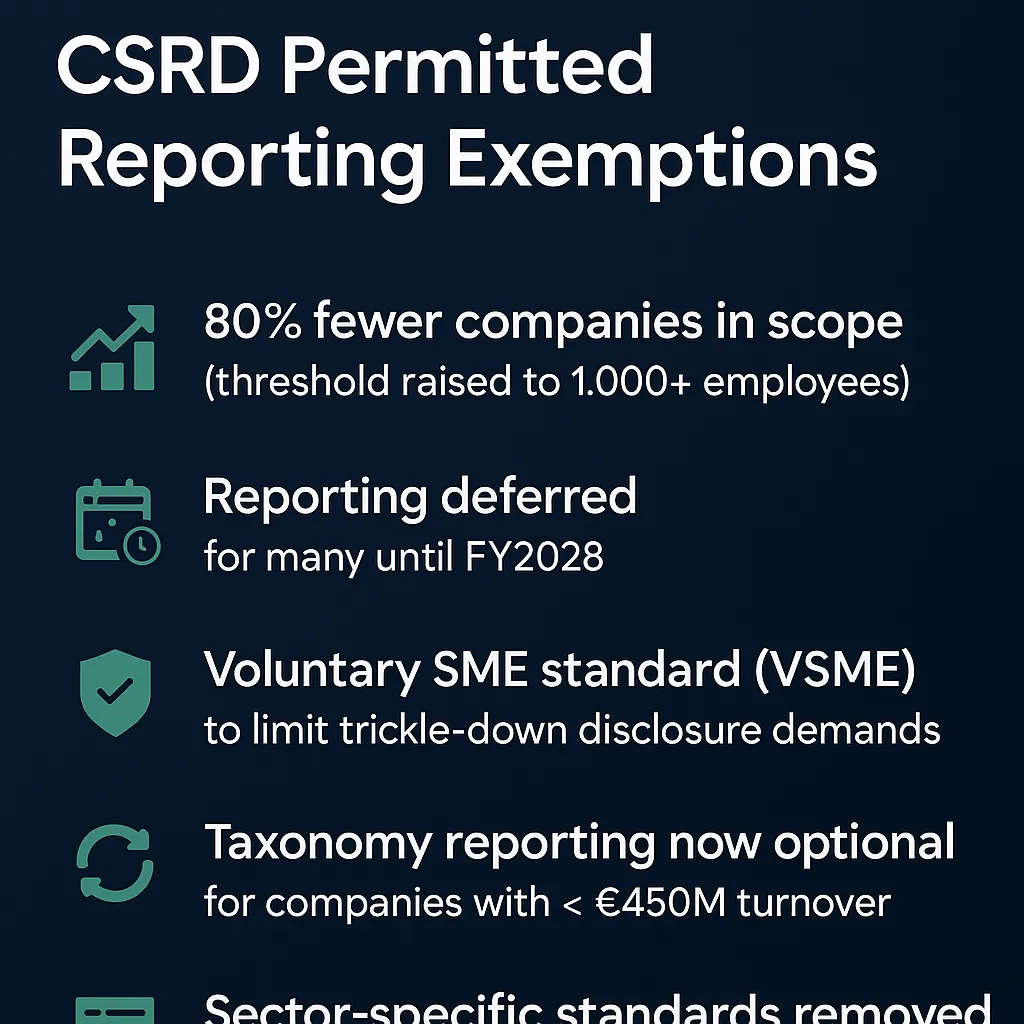
Update (September 2026): The Commission adopted the revised ESRS on 3 July 2026. Mandatory datapoints fall by more than 60% and all voluntary datapoints are removed; EFRAG's 28 August 2026 draft list runs to about 530 datapoints with a draft XBRL taxonomy (comments to 23 October). The delegated act enters into force on 10 November 2026 absent objection and applies to financial years beginning on or after 1 January 2027; for FY2026 a company may stay on Set 1, early-adopt in full, or apply Set 1 with selected reliefs.
Full analysis: CSRD After the Omnibus.
The ESRS standards are reporting standards for sustainability within the EU. The ESRS standards are an integral part of the CSRD, the Corporate Sustainability Reporting Directive of the European Parliament and the Council. This means that the ESRS reporting standards are mandatory. The adoption of the first set of 12 standards by the Commission is considered a significant step to promote sustainable practices and transparency in companies and to contribute to their comparability. This is because the new reporting requirements herald major changes in sustainability reporting and these will affect around 50,000 companies based in the EU. However, subsidiaries, branches abroad and companies that carry out a large part of their business activities in the EU area may also be indirectly affected, which is why the scope of impact can be significantly broader.